Density, distribution function and random generation for the vine based distribution.
Usage
dvine(x, vine, cores = 1, log = FALSE)

pvine(x, vine, n_mc = 10^4, cores = 1)

rvine(n, vine, qrng = FALSE, cores = 1, x_cond = NULL, conditioning_set = NULL)
Arguments
- x
evaluation points, either a length d vector or a d-column matrix, where d is the number of variables in the vine.
- vine
an object of class
"vine_dist".- cores
number of cores to use; if larger than one, computations are done in parallel on
coresbatches .- log
if
TRUE,dvine()returns the log-density instead of the density. The density is accumulated in log space either way and only exponentiated at the end;log = TRUEskips that last step. The joint density is a product over the margins and the vine edges, so it underflows to0in high dimensions or under strong dependence while its logarithm is still an ordinary double.- n_mc
number of samples used for quasi Monte Carlo integration.
- n
number of observations.
- qrng
if
TRUE, generates quasi-random numbers using the multivariate Generalized Halton sequence up to dimension 300 and the Generalized Sobol sequence in higher dimensions (defaultqrng = FALSE).- x_cond
optional conditioning values for
rvine()on the original data scale. A vector or one-row object is repeatedntimes; alternatively, supply ann-row matrix or data frame for observation-specific conditioning values. IfNULL,rvine()performs unconditional simulation.- conditioning_set
variable indices or names corresponding to the columns of
x_cond. WhenNULL, the columns correspond to the last variables of the current copula order. Discrete left limits are computed internally from the fitted margins.
Value
dvine() gives the density, pvine() gives the distribution function,
and rvine() generates unconditional or conditional random deviates.
The length of the result is determined by n for rvine(), and
the number of rows in u for the other functions.
The vine object is recycled to the length of the
result.
Details
See vine for the estimation and construction of vine models. Here, the density, distribution function and random generation for the vine distributions are standard.
The functions are based on dvinecop(), pvinecop() and rvinecop() for
vinecop objects. Margins are evaluated through dmargin(), pmargin(),
and qmargin(). Methods are provided for margins fitted by vine() and for
the fixed stats::Distributions specifications accepted by vine_dist().
Examples
# specify pair-copulas
bicop <- bicop_dist("bb1", 90, c(3, 2))
pcs <- list(
list(bicop, bicop), # pair-copulas in first tree
list(bicop) # pair-copulas in second tree
)
# set up vine copula model
mat <- rvine_matrix_sim(3)
vc <- vine_dist(list(stats_margin("norm")), pcs, mat)
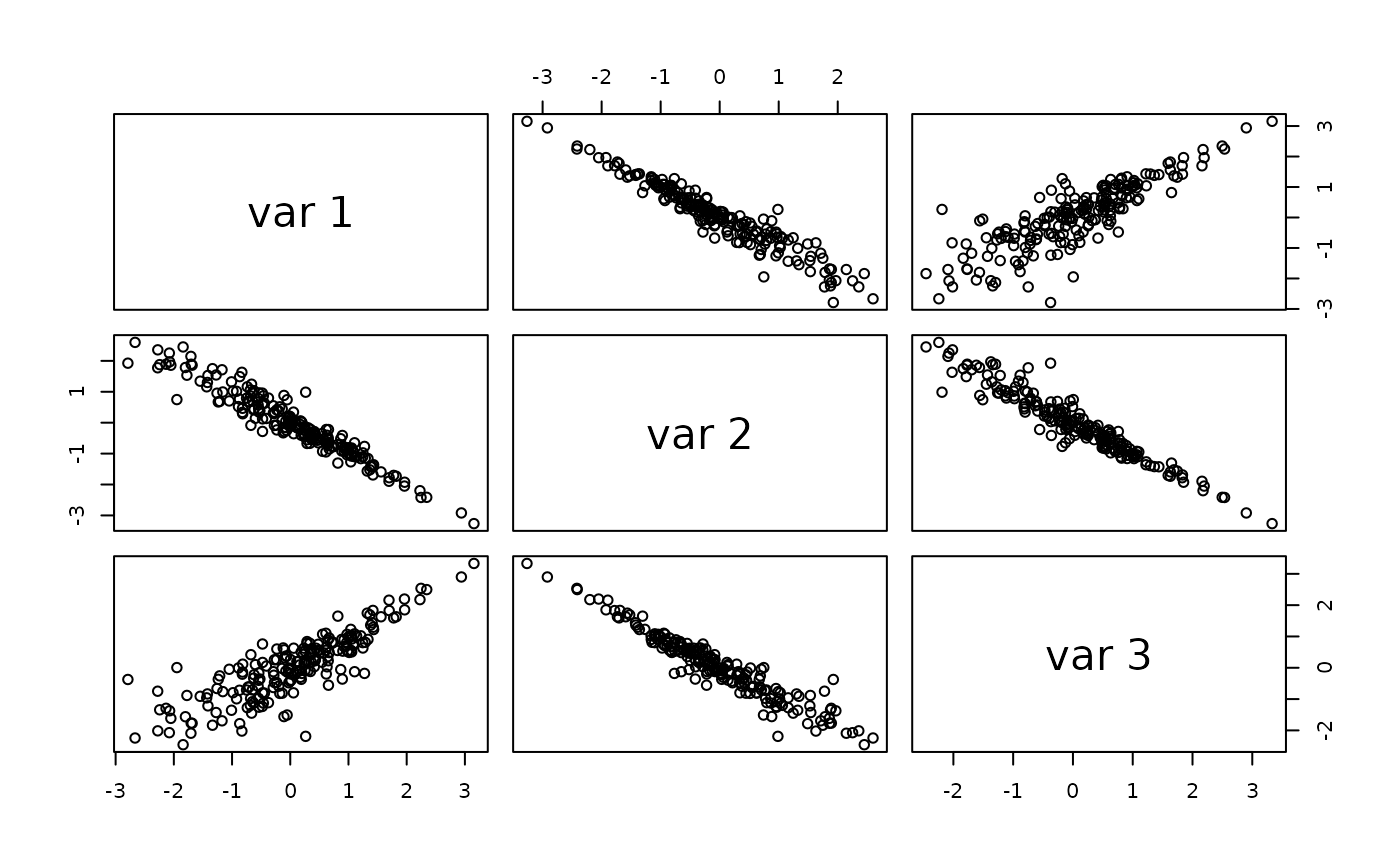
# simulate from the model
x <- rvine(200, vc)
pairs(x)
 # evaluate the density and cdf
dvine(x[1, ], vc)
#> [1] 0.3210905
pvine(x[1, ], vc)
#> [1] 1e-04